Updated
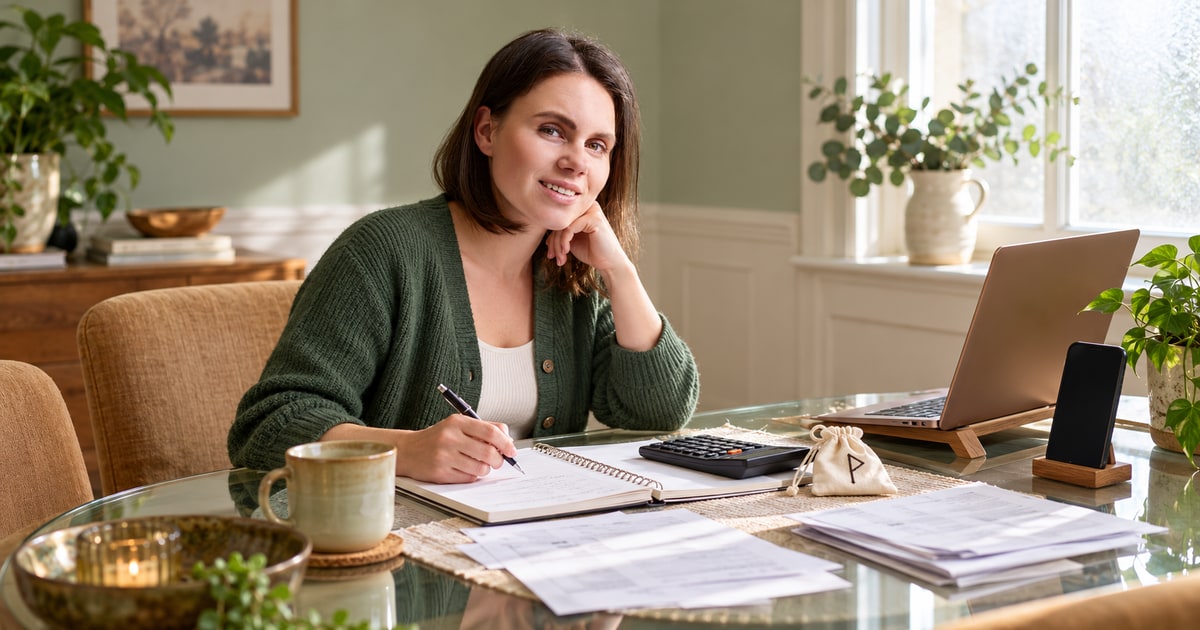
If runes are meaningful to you, a short reflection can be a gentle way to begin a money task you have been putting off. Let it help you name the concern, then give income, expenses, debt terms and payment dates their own space on the page. A symbol can offer a personal association; your records show what you can afford.
You can keep a spiritual practice without asking it to guarantee financial gain.
Financial difficulty can involve low income, changing work, illness, caring responsibilities, high costs and other pressures. It is not evidence of bad karma, a family curse or a failure to feel grateful. You do not need a psychic reading to diagnose the spiritual cause of a shortfall.
Give reflection and records different jobs
Our introduction to rune reflection explains the symbolic approach. Try a question about your own attention: “Which money task am I avoiding?” Write the association in a reflection column. In a separate column, list the information needed before taking action.
The examples below turn a feeling into something you can check. They are not readings of particular rune symbols or a personalized financial plan.
1. Next month feels uncertain
- Concern or association
- I feel uncertain about next month.
- Record to check
- Expected income and bills due
- Possible practical step
- Make a dated cash-flow list.
2. A charge is easy to miss
- Concern or association
- A regular charge feels easy to overlook.
- Record to check
- Recent account statements and subscription terms
- Possible practical step
- Check whether it is still wanted and how cancellation works.
3. A payment needs explaining
- Concern or association
- I need help understanding a payment.
- Record to check
- The agreement and current statement
- Possible practical step
- Prepare a specific question for the provider.
No rune draw overrides the account balance, a contract or the cost of an essential need. If a symbol brings up a strong feeling, you can write it down without making a purchase, transfer or borrowing decision that day.
Look at dates as well as totals
A month can look balanced overall while a bill falls due before the next payment arrives. Put expected incoming money and outgoing bills on a calendar, marking uncertain amounts as estimates. Use posted statements and current terms when available.
A simple timing example
Imagine that income is expected on Friday, but a payment is due on Wednesday. A monthly total can hide those two days. The useful next step is to verify both dates and the agreement’s terms, then ask the provider about any available options through its official contact channel. A rune association might remind you to make the call; it cannot confirm an extension or change the due date.
The U.S. Consumer Financial Protection Bureau’s Your Money, Your Goals toolkit includes income and spending trackers, a bill calendar and cash-flow worksheets. These tools can help organize information to discuss with an appropriate adviser or service provider; they do not make a shortfall disappear.
Choose one task with a clear finish
A manageable finish is more useful than a promise to “fix everything.” Choose one task you can describe plainly:
- Gather the record. Find the latest statement, bill or agreement rather than relying on a remembered amount.
- Write one question. For example, ask what an unfamiliar charge covers or which date a payment is due.
- Use a verified channel. Contact details on the provider’s official site or your own statement are a better starting point than an unsolicited message.
- Note the answer and next date. Keep any confirmation with the record. If the question remains unresolved, record what still needs checking.
You can use an affirmation as a reminder to begin—“I can look at one bill”—without treating it as a promise of income. The task can be small enough to complete without a paid spiritual service.
If essentials exceed the money available, the issue needs practical support and a realistic review of options. Seek reputable local assistance or qualified financial guidance for your circumstances. Needing that help does not mean you have failed at a spiritual practice.
Keep symbolic meaning from becoming a sales claim
Do not pay someone to remove a supposed money curse or unlock a guaranteed windfall. Avoid borrowing to fund a ritual or reading intended to solve debt. A meaningful personal practice does not need an escalating purchase.
Our guide to rune-healing stories and their limits distinguishes historical storytelling from evidence. Apply the same care to money: keep the reflection if it is useful, then use verifiable information to make the decision.
Frequently asked questions
1. Can positive thinking or a rune guarantee financial gain?
No. A reflection does not establish income, affordability or future returns. Check actual records and do not use a reading as investment or borrowing advice.
2. Does financial hardship mean I have a money curse?
No. A shortfall is not evidence of a curse, bad karma or failed belief. Avoid anyone charging to remove a supposed spiritual cause or promising a guaranteed windfall.
3. What should I check before acting on a money reflection?
Check expected income, bills, payment dates, current statements and relevant agreement terms. Keep symbolic associations separate from information used to decide what you can afford.
4. What if my essential costs exceed the money available?
Seek reputable local assistance or qualified financial guidance for your circumstances. A ritual will not supply the missing income; avoid borrowing to pay for a reading intended to solve debt.
Budgeting and saving are fundamental practices that can lead to financial stability. While the concept of changing one’s mindset is important, tangible actions are equally crucial.
The Law of Attraction’s role in financial success can be compelling. However, I believe that a combination of mindset change and concrete financial strategies is necessary for real improvement.
The suggestion to consult a psychic for financial clarity is unconventional. It’s important to critically evaluate such advice and balance it with more traditional financial planning methods.
The article’s connection between karma and finances is a unique perspective. I am skeptical, though, about how much past life karma can affect current financial situations.
Generational financial habits are indeed influential. Analyzing our parents’ approach to money might offer valuable insights. However, I am curious about the practical steps to break these cycles.
The emphasis on a positive money mindset is intriguing. It’s interesting to consider how our thoughts can impact our financial health. I wonder how much of this is rooted in psychology.